Insurance is just math. People hate doing math. Can we do the math?
 kara.armstrong6min
Historically, your healthcare has been limited to your health insurance, and that insurance decision was made well before you got to the table—your employer tried to pick a few plans that covered the best and worst outcomes across all of their employees, but everyone ended up in a one-size-fits-none situation.
Thatch is changing that by unlocking plan choice: your employer sets a health budget, then you choose your own plan from tens or hundreds of options. Any money you don't spend on insurance, you get to keep and spend on care: copays, prescriptions, blood tests, therapy, imaging, and even cash paying for providers who don't take the insurance you end up on.
That choice is empowering, but it can also be scary! Choosing health insurance is like a role-playing game, where people run the scenario analyses of "if I make move X, then Y will happen" to figure out what'll work best; but getting one move wrong in that "game" has real-world implications to your family and your health.
So we built a product to help: It asks about your health priorities, then uses those and the money your employer is offering to narrow those hundreds of options down to the few that best fit your life.
It starts with you
We can't recommend the right plan until we understand the person choosing it.
We ask about the things that actually decide whether a plan fits you: the doctors, hospitals, and prescriptions you want to keep; the conditions you manage and how often you need care; and whether there's anything on the horizon that we should take into account, like pregnancy, a needed surgery, or prepping for young kids' inevitable ER visits. (This information is never shared with anyone—neither your employer nor the insurance company you pick. We can't even see it ourselves on the Thatch side.)
Choosing health insurance is a financial decision as much as a medical one, so we ask about that side too: how much you can comfortably pay each month, and whether you'd rather save part of your budget for later or spend more now to protect against a big bill.
Along the way, your answers show up as a dynamic rubric that both helps you to see how your priorities map to your budget (on a $, $$, $$$, or $$$$ scale) and gives us guidance on what we should focus on in our recommendations.
Treating healthcare as a line item in your personal budget
Usually when people are picking insurance, they bust out some extensive spreadsheet calculations. What they're really trying to do is understand what they can afford relative to their personal budget, and what that affordable option looks like in reality. With personalized budget guidance, we've done the math for you.
Every recommendation leads with one number: our estimate of what the plan will actually cost you per month, all in. It rolls in the insurance cost, the copays, the prescriptions, and the care you told us is coming, with your health budget subtracted. That all-in cost is the best way to compare every plan available to you on a like-for-like basis.
Then we explain it in words, in terms of what we already know you care about. For someone with diabetes who wants to keep their doctor, that sounds like:
This plan covers your insulin, keeps Dr. Smith in your network, and runs about $75 to $150 a month for your regular care. Your budget covers roughly $200 more than the plan costs, so your routine diabetes care is covered without paying out of pocket.
What goes into that one number
We assign a dollar amount to each line item in your rubric:
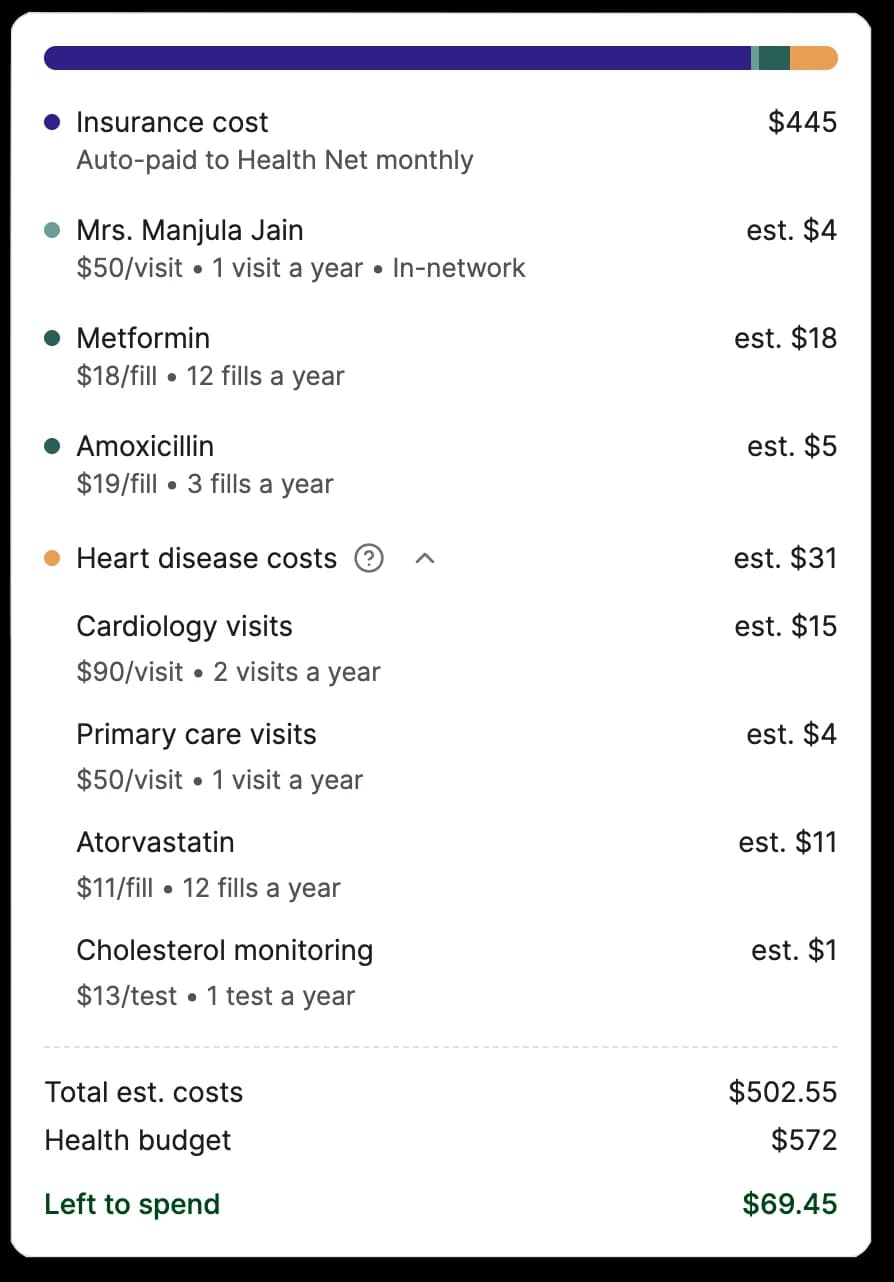
Every plan comes with a stack of dense documents: Summary of Benefits, formularies, provider networks, deductibles, copays, coinsurance, out-of-pocket maximums, referral rules, exclusions… We read them for you, then use that plan's actual rules—how much you pay before coverage kicks in (your deductible), what you owe for each visit or prescription after that (your copay or coinsurance), and the most you'd ever have to pay in a year (your out-of-pocket maximum)—and apply them to the care that you've told us is important to you.
We'll even estimate what it'd look like for you to pay directly for doctors and prescriptions that that particular plan doesn't cover, using national averages for care.
A health priority isn't a cost on its own, so we use health episodes to turn them into one. Say you tell us you're managing heart disease: we map that to a year of monthly prescription fills, regular cardiology visits, and the routine labs that go with them. (Thatch isn't making any clinical recommendations on the right course of treatment for your particular conditions or priorities. We use a standard set of assumptions for each care episode, so your actual costs may be higher or lower.)
Cost isn't the whole story, though. We also build a fingerprint for every plan (a profile of its core features), and score how closely that fingerprint matches the priorities you gave us. There's often a plan that's only a few dollars more each month but covers far more of the care you actually use, and you'd never know to look for it.
That fit score and your cost estimate combine into one overall result.
Then we run one last pass over every plan, using a clustering algorithm to find the ones that genuinely stand apart from the pack. That's why some people see one recommended plan and others see three, and why one person's picks might all be bronze plans while others all come from a single insurance company. And if there's genuinely no great fit for your needs in your area, we can tell you that, too.
Sometimes the best answer isn't only insurance
Your health budget also frees you up from depending only on your plan to get the care you need. Sometimes a cheaper plan plus some add-ons (like the products and services in Thatch Market) beats a richer plan on its own.
So we rank plans and bundles side by side, on the same all-in cost basis:
- Gold plan: $973/mo
- Silver plan + continuous glucose monitor + endocrinologist copay support: $923/mo
- Gold plan + dental + vision: $1,079/mo
We make those tradeoffs obvious, and tell you when the cheaper plan is the better one.
You're never choosing alone
Most members get to a confident choice on their own: 91% pick their plan without needing help. For everyone else, or anyone who just wants a second opinion, our licensed advisors are available for one-on-one calls before you decide.
Because every recommendation explains its own reasoning, an advisor can walk through exactly why we suggested one plan over another, and help you decide whether you weigh things differently.
And your employer will love it :)
Employers don't want to be experts on the hundreds of plans their employees can access through Thatch. They want to offer great benefits, keep costs predictable, and know their team is taken care of.
Traditional group plans force one coverage decision on everyone, and forced your benefits admin into also being your insurance advisor. Thatch lets them focus on being an expert in their employees, instead. (And 93% of those employees say our experience is good or great, so they can rest easy in that handoff.)
That's what Thatch is: personalized health benefits, built on the details of every plan, a real understanding of what each person needs, and cost estimates honest enough to trust.